Life • Health • Financial Services
Protecting What You Have, Who You Love, and What’s Ahead!
Business Owner's Policy

One policy for property, liability and business income.

A Business Owner's Policy, commonly called a BOP, packages several core business insurance coverages into one policy for eligible businesses.

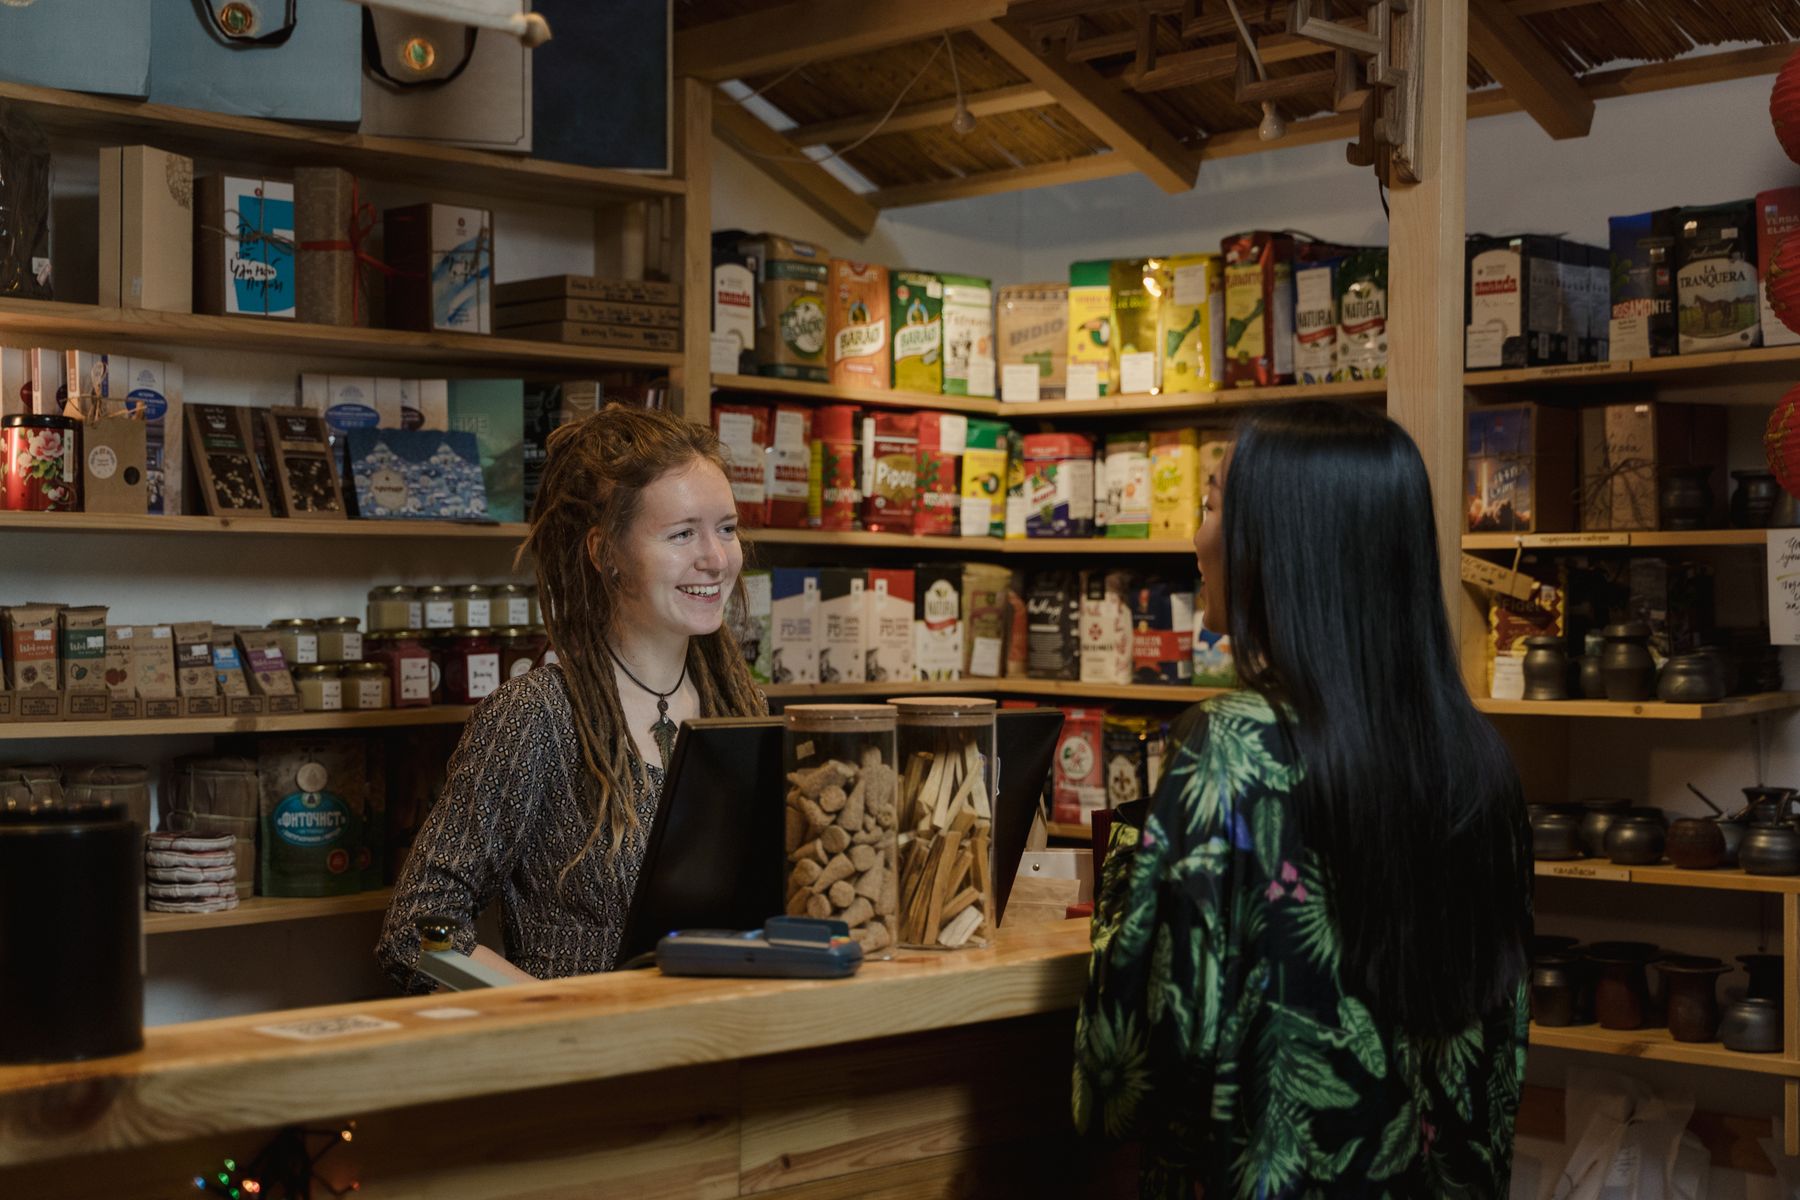
Shopkeeper assisting a customer inside a stocked store
Business Owner's Policy Three core coverage areas brought together for eligible businesses.
01
General Liability Third-party claims
02
Commercial Property Business property and equipment
03
Business Income Certain covered interruptions
Packaged Business Insurance

A BOP combines several everyday business coverages.

Rather than purchasing certain property and liability coverages separately, eligible businesses may be able to use one Business Owner's Policy.

The exact policy, limits, extensions and eligibility rules depend on the insurer and the type of business.

Core BOP Coverage

Three parts working inside one policy.

Individual BOP forms differ, but general liability, business property and business income are common core coverage areas.

01

General Liability

General liability can address qualifying claims involving third-party bodily injury, property damage and certain other liability allegations.

EXAMPLE A customer alleges injury after a covered incident at the business.
02

Commercial Property

Property coverage can address qualifying covered loss to insured buildings, equipment, inventory, furniture and other business property.

EXAMPLE A covered fire damages insured equipment and inventory.
03

Business Income

Business income coverage may help with qualifying income loss and certain continuing expenses while operations are suspended after a covered property event.

EXAMPLE A covered property loss temporarily prevents the business from operating.
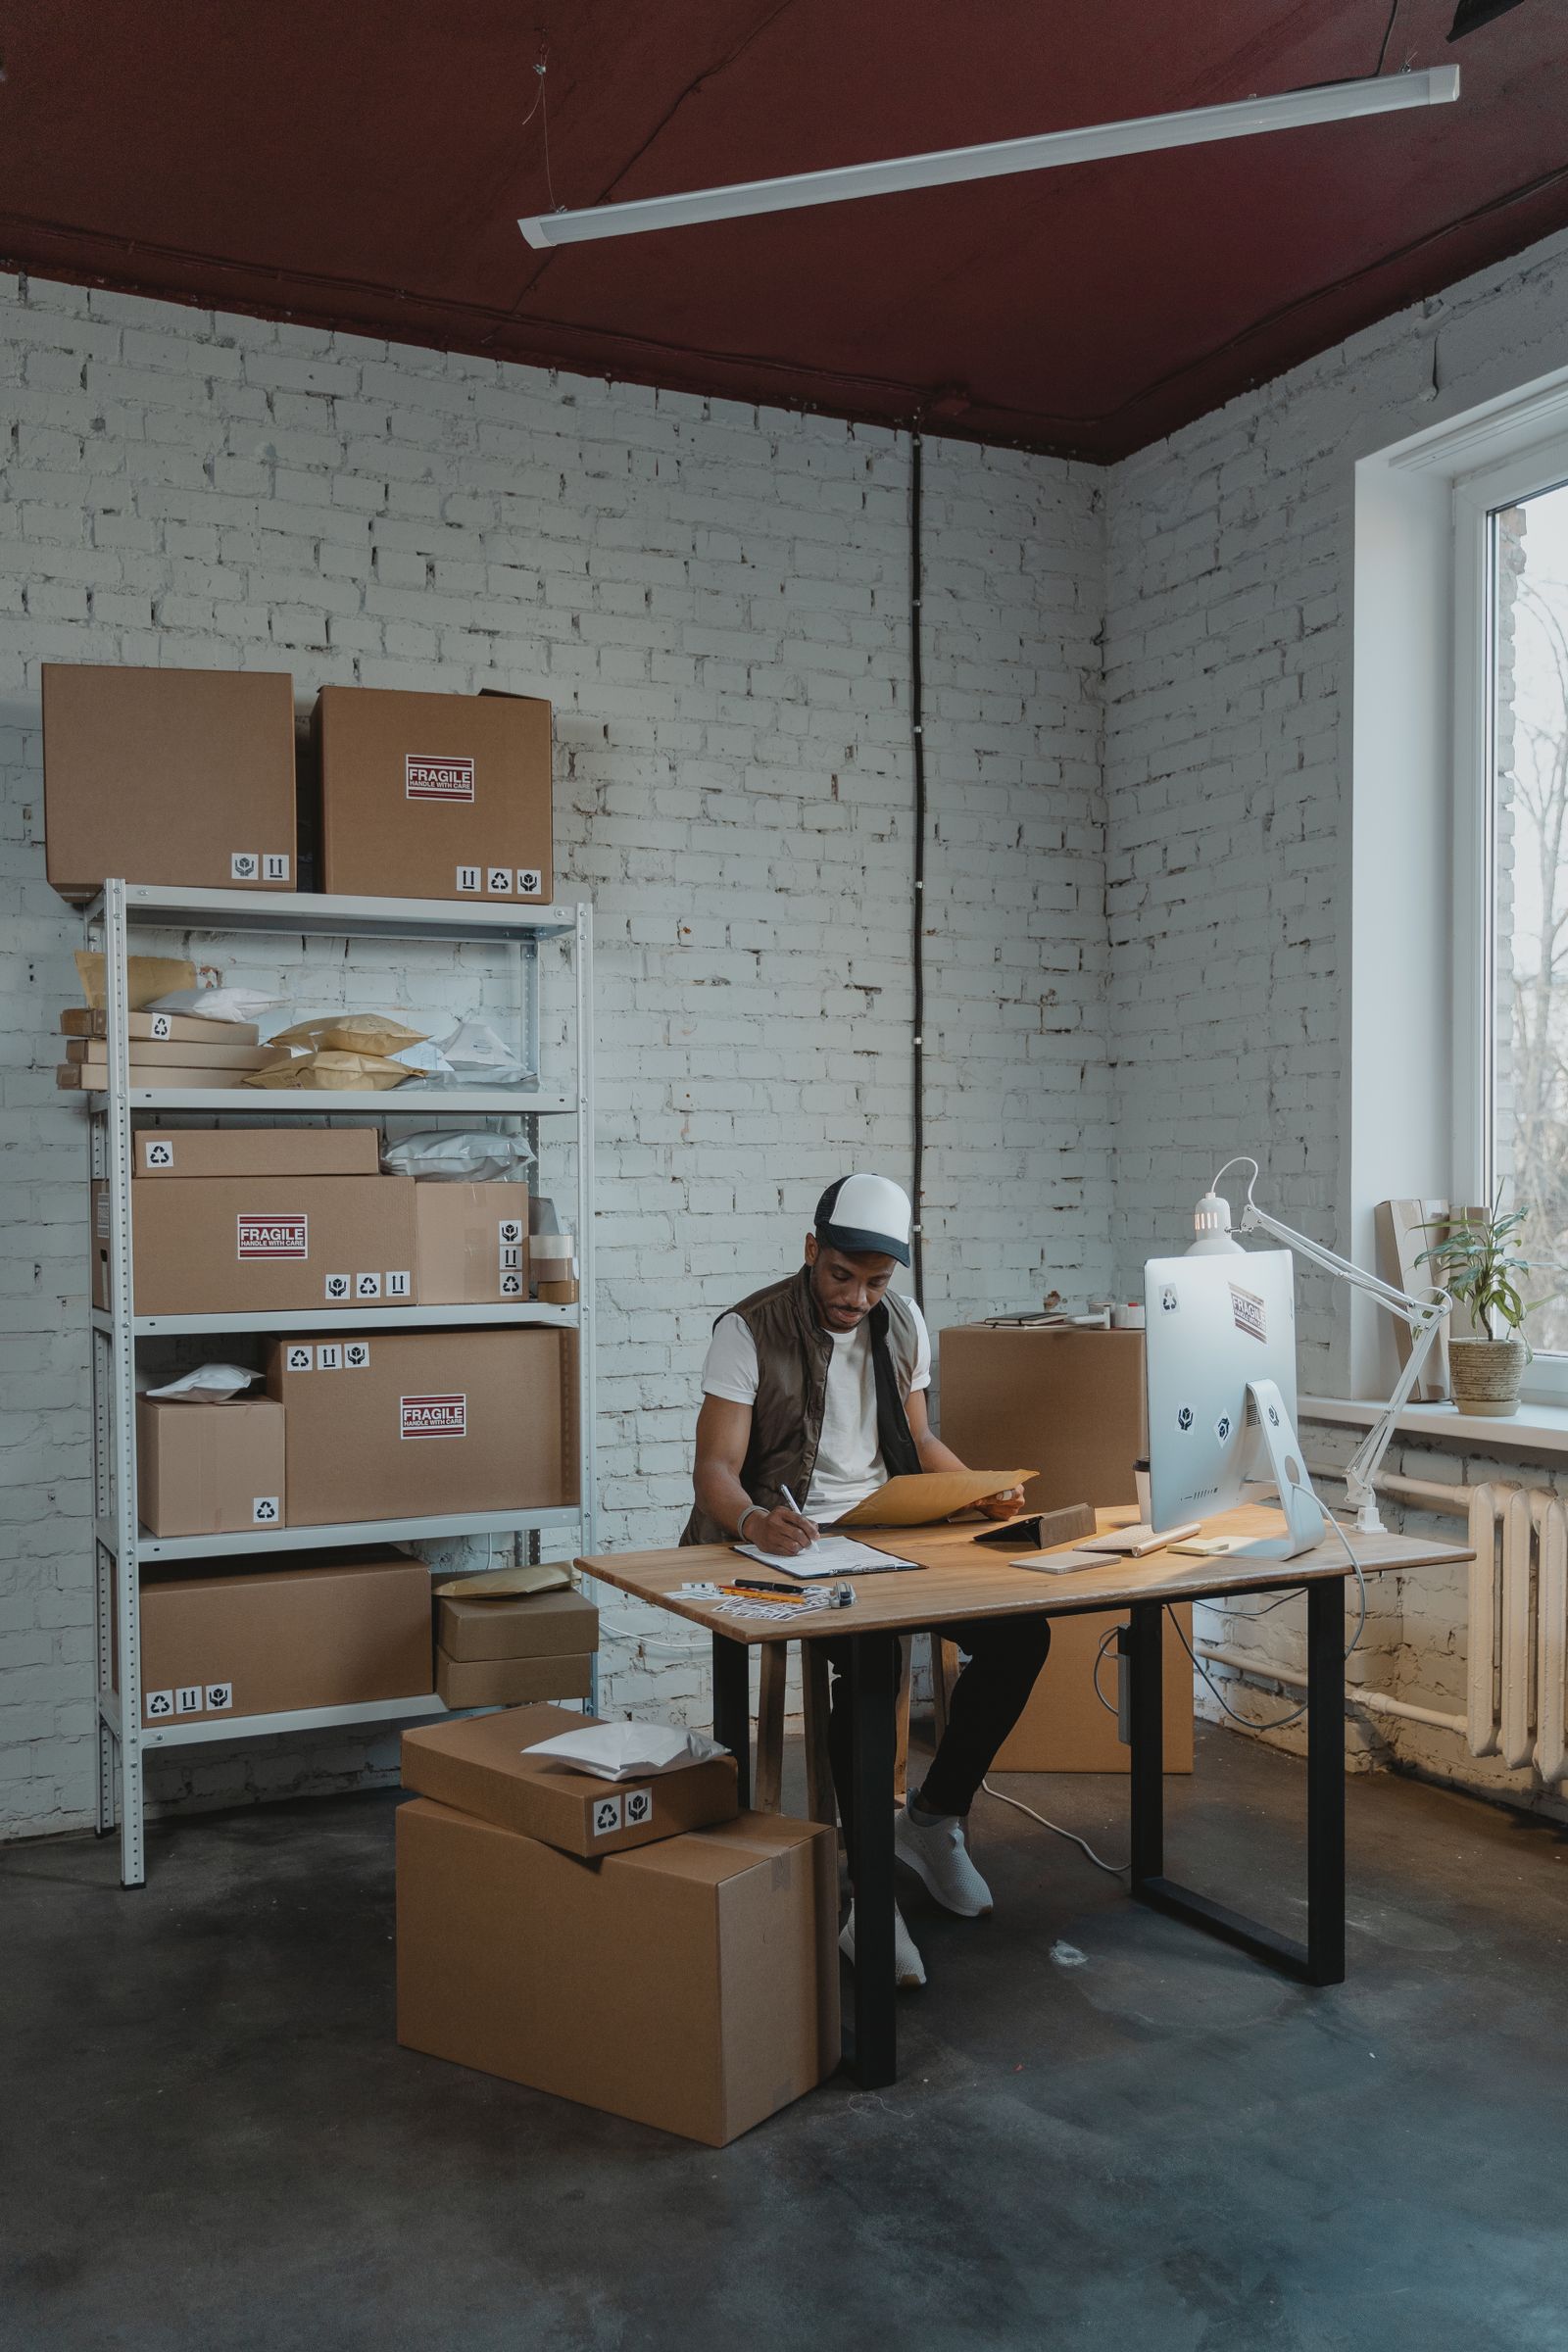
Worker organizing packages inside a small warehouse workspace
One Business Event A single covered loss can affect property and business operations.
How the Coverage Connects

Property damage can affect more than the property itself.

When a covered event damages business property, the business may also lose the ability to operate normally. Different parts of a BOP can address different parts of that loss.

01
Physical property

Commercial property coverage can address qualifying physical damage to insured property.

02
Temporary closure

A covered property event may force operations to stop while repairs are underway.

03
Lost income

Business income coverage may respond to qualifying income loss during the covered suspension.

04
Liability remains separate

General liability addresses qualifying third-party claims rather than damage to your own business property.

BOP Eligibility

A BOP is designed for certain eligible businesses.

Eligibility rules vary by insurer. Business activity, size, property and other risk information may all be considered.

01

Retail Businesses

Eligible shops and retail operations may need both property and liability coverage in one policy.

02

Offices

Certain office-based businesses may qualify depending on business activity and carrier rules.

03

Service Businesses

Some qualifying service businesses may use a BOP for core property and general liability needs.

04

Property-Based Operations

Certain eligible businesses with equipment, inventory or physical locations may qualify.

Business Property

Look at what the business would need to replace.

A business can depend on far more than the building itself. Equipment, inventory and other physical assets may form part of the property review.

01 Equipment

Machinery, computers, tools and other insured equipment.

02 Inventory

Qualifying stock and products held by the business.

03 Furniture & Fixtures

Desks, shelving and other insured business furnishings.

04 Building Improvements

Certain qualifying improvements made to occupied premises.

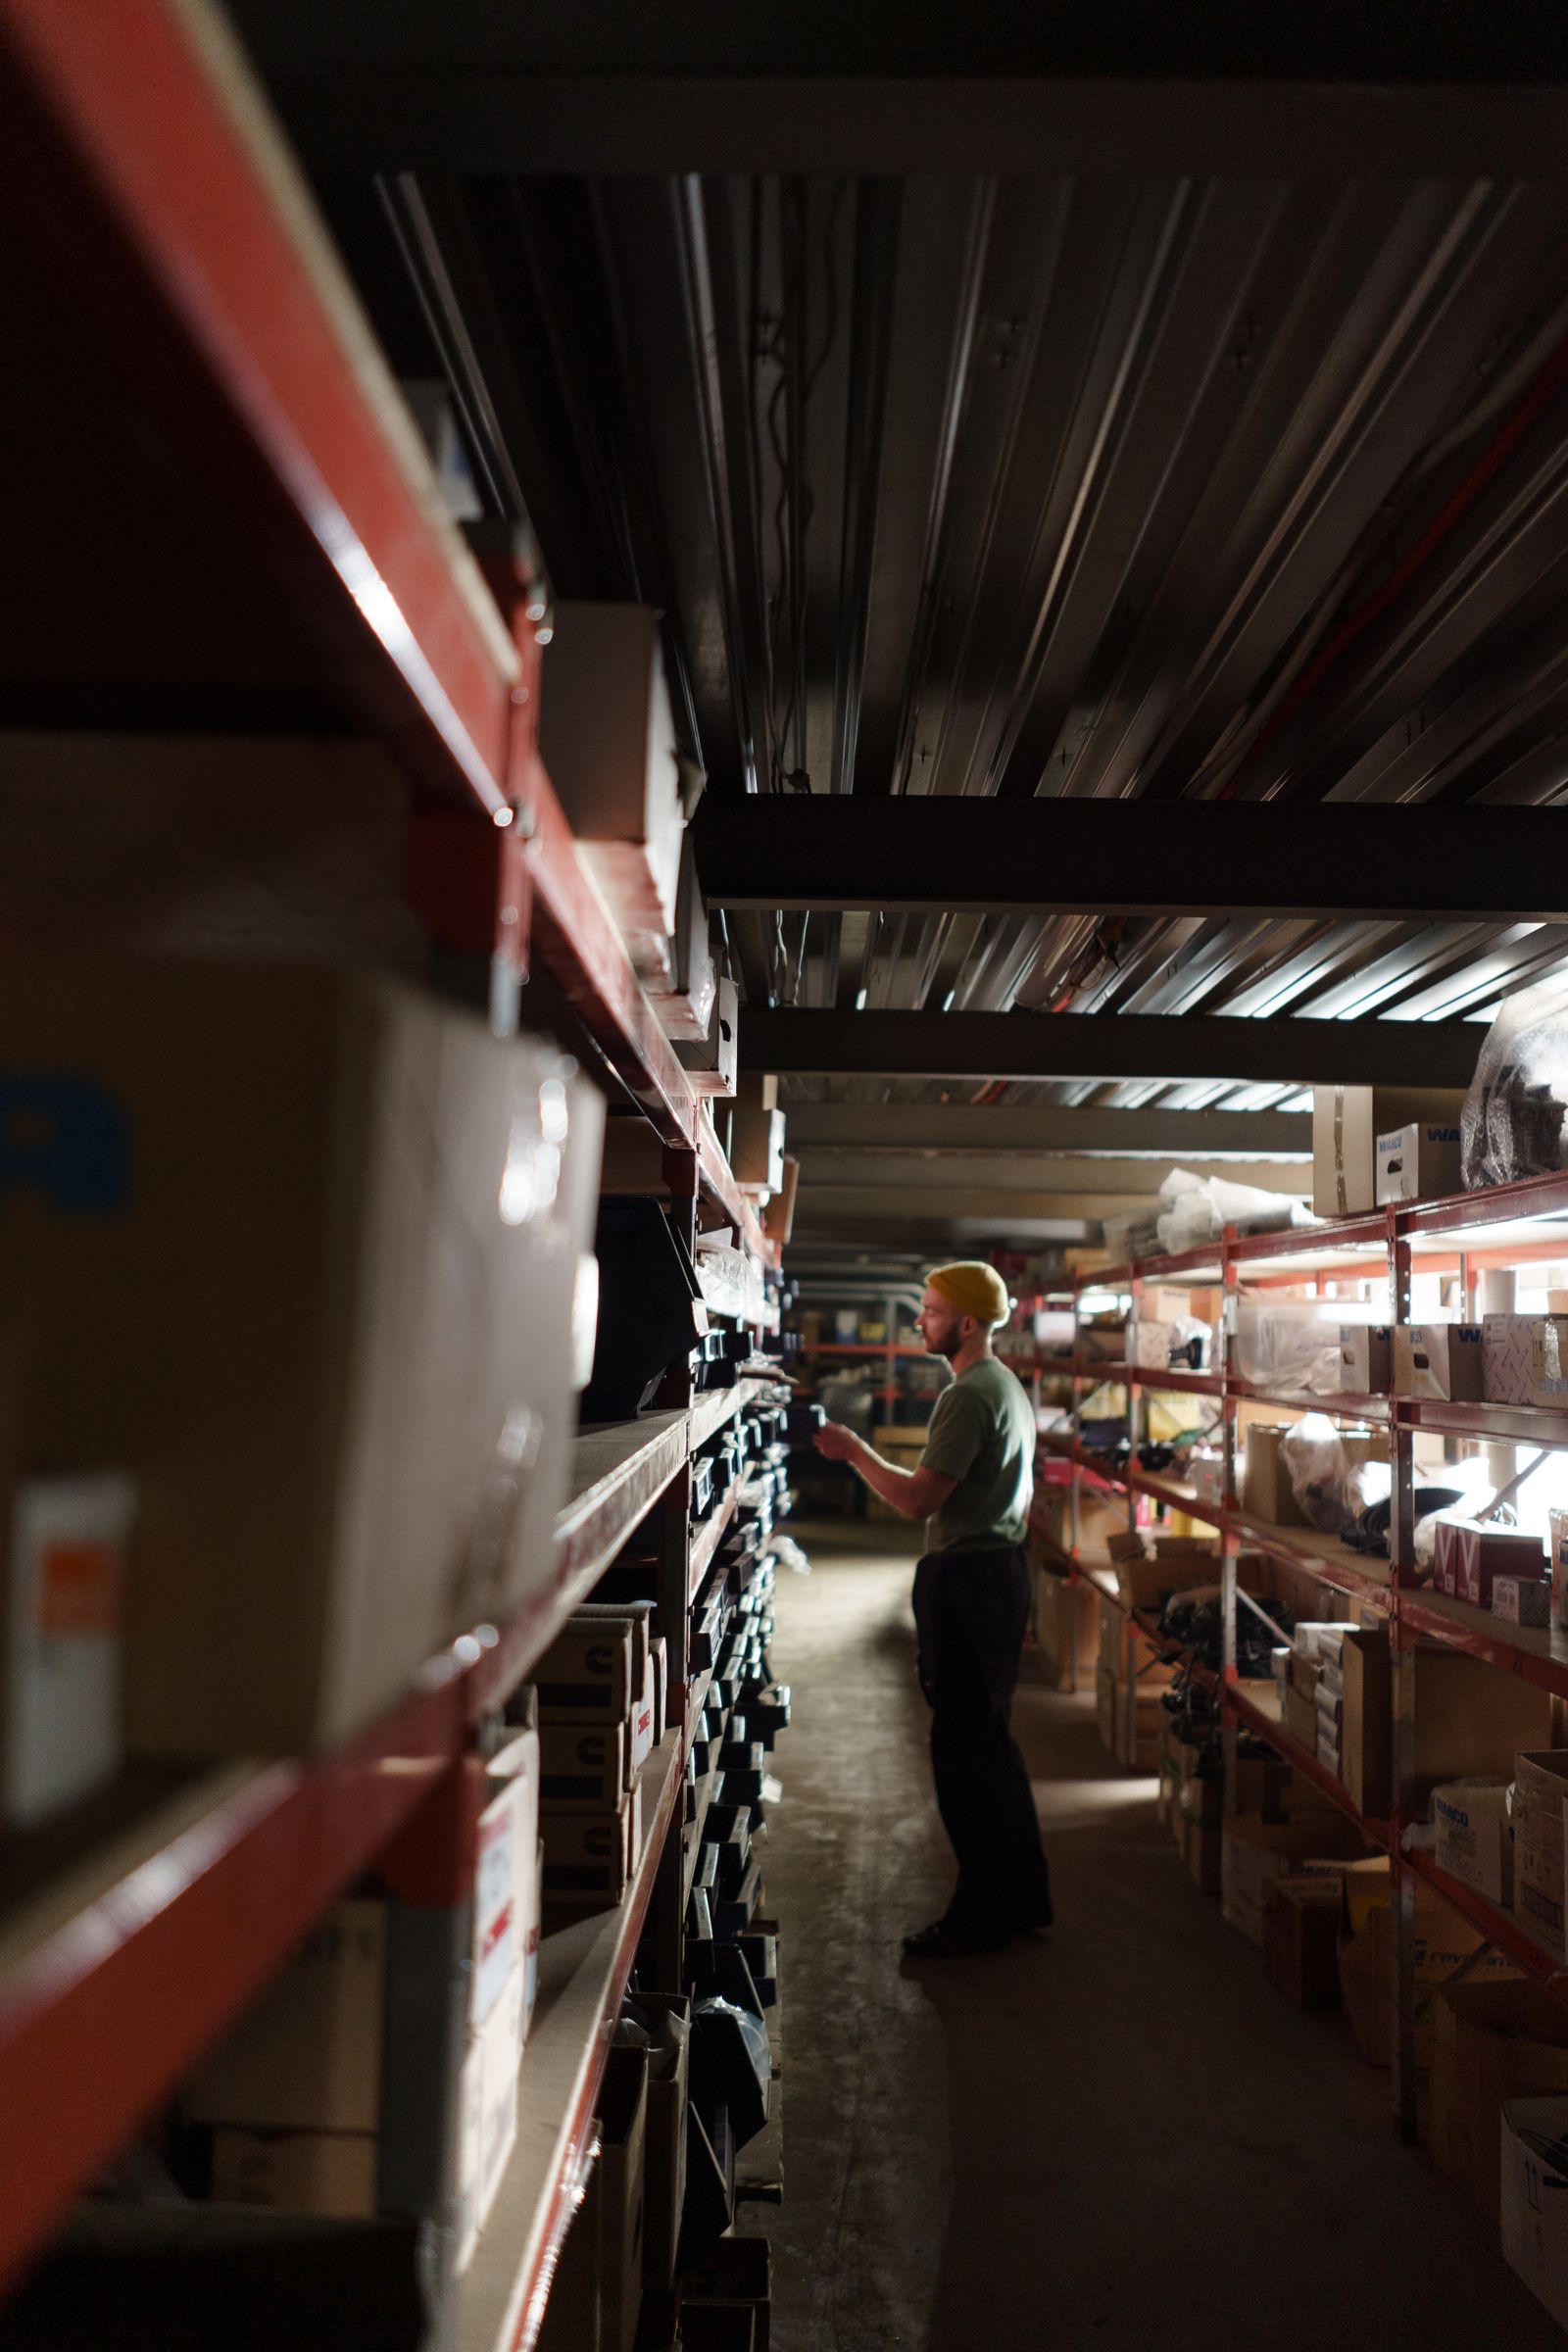
Worker checking stocked shelves in a warehouse
Property Coverage Inventory and equipment can be central to keeping a business running.
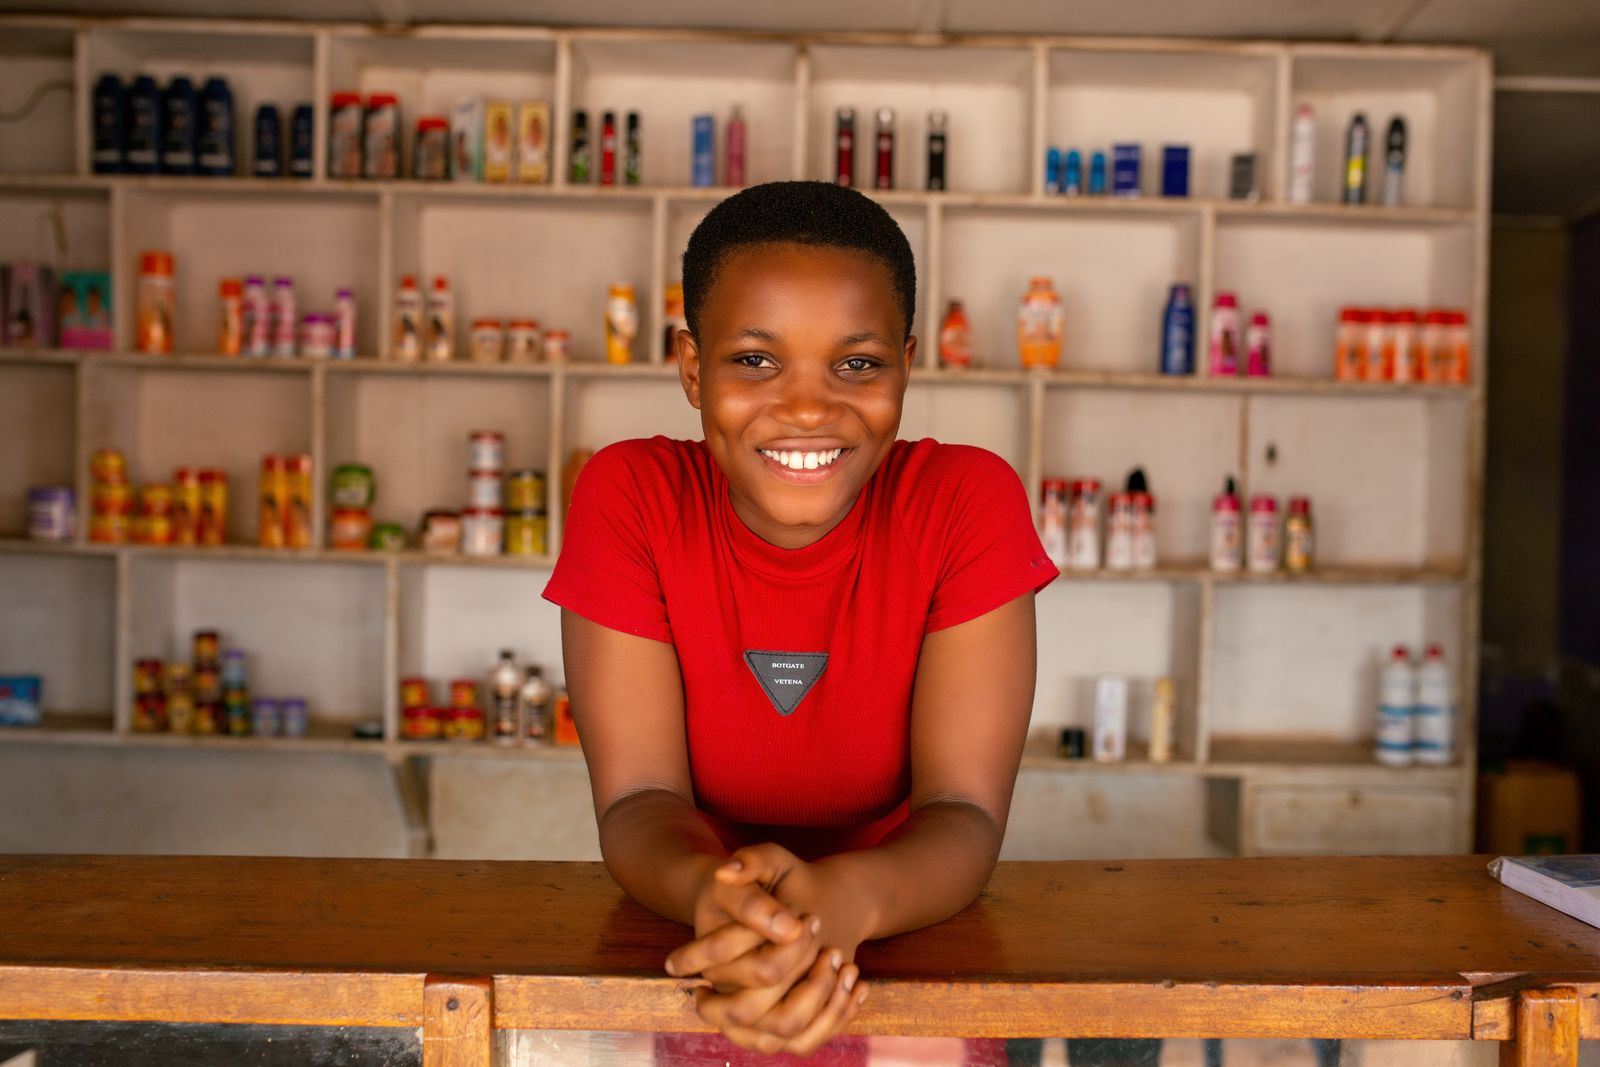
Shopkeeper standing behind a counter inside a stocked store
Business Income

A closed business can still have bills to pay.

Business income coverage may help with certain financial losses when a covered property event causes qualifying operations to stop.

01
Lost business income

Coverage may address qualifying income that would otherwise have been earned.

02
Continuing expenses

Certain ongoing expenses may qualify according to policy terms.

03
Temporary operating costs

Certain extra expenses tied to continuing operations elsewhere may qualify under applicable coverage.

04
Covered cause required

Business income coverage depends on the policy trigger and covered cause of loss.

Beyond the Core BOP

Some business risks may need separate coverage.

A Business Owner's Policy does not automatically replace every other type of commercial insurance a business may need.

01

Commercial Auto

Business-owned or qualifying business-use vehicles may require separate commercial auto coverage.

02

Professional Liability

Professional services and alleged errors or omissions may require separate coverage.

03

Workers' Compensation

Employee-related coverage is handled separately and requirements differ by state.

04

Cyber Liability

Businesses handling digital systems or customer information may consider separate cyber coverage.

Eligibility & Quoting

The insurer will look at the business itself.

01

Business Type

The work performed and industry can affect BOP eligibility.

02

Property

Locations, equipment, inventory and property values may be reviewed.

03

Revenue & Operations

Business size and operating information may form part of carrier eligibility.

04

Claims History

Prior insurance and claim information may be requested during underwriting.

Policy Review

A package policy still needs a careful review.

Combining coverage in one policy does not make every limit, exclusion or condition identical between insurers.

01
Liability limits

Check the limits applying to qualifying liability claims.

02
Property values

Review insured buildings, equipment and inventory values.

03
Deductibles

Check applicable deductibles for covered property losses.

04
Exclusions and extensions

Read what is excluded and which additional coverage has been added.

Business professionals in formal attire meeting in an office
Getting Started

Start with the property, liability and income risks.

Basic business information can help determine whether a BOP may fit the operation.

01

Describe the business.

Share business activity, locations and normal operations.

02

Review business property.

Identify equipment, inventory, furniture and other property that may need insurance.

03

Review liability and income.

Consider customer activity, liability risks and the effect of a covered shutdown.

04

Review the policy.

Check limits, deductibles, covered causes, exclusions and any added coverage.

BOP FAQ

Common questions.

BOP eligibility and policy terms vary by business and insurer.

A Business Owner's Policy, or BOP, is a packaged commercial insurance policy commonly combining general liability, commercial property and business income coverage for eligible businesses.

BOPs commonly include general liability, commercial property and business income or business interruption coverage. Exact policy terms differ by insurer.

No. Eligibility depends on insurer guidelines and can involve the type of business, size, property, operations and other risk information.

Commercial auto is generally handled separately from the core BOP. Businesses with vehicles should review their commercial auto needs separately.

Workers' compensation is generally separate from the core BOP. Employer requirements differ by state and business situation.

Information may include business activity, locations, property values, equipment, inventory, revenue, prior coverage and claim history.

Business Owner's Policy

Put core business coverage together in one conversation.

Tell Trinity about your business, property and operations to begin reviewing available BOP options.

Coverage availability, eligibility, policy terms, limits and exclusions vary by product and carrier. Contact Trinity for product availability and coverage details.