Coverage built for the road your business runs on.
Truck insurance can help protect qualifying commercial vehicles, business liability, transported cargo and other trucking exposures based on how your operation works.
A commercial truck carries more than the vehicle itself.
Trucking operations can involve vehicle liability, expensive equipment, freight, non-owned trailers, contractual requirements and regulatory filings.
The policy structure should reflect what you drive, what you haul, where you operate and how the truck is used.
Coverage can address several parts of the operation.
Available coverage differs by insurer, vehicle, business activity and applicable state or federal requirements.
Commercial Auto Liability
Liability coverage can address qualifying bodily injury or property damage claims arising from operation of an insured commercial truck.
Physical Damage
Physical damage protection can address qualifying damage to an insured truck from covered collision and other listed causes of loss.
Motor Truck Cargo
Cargo insurance can protect qualifying goods being transported when covered loss or damage occurs in transit.
Trailer Interchange
Coverage may protect qualifying non-owned trailers in your possession under a trailer interchange agreement.
Non-Trucking Liability
Certain leased owner-operators may use non-trucking liability for qualifying personal use of the truck when they are not operating for business.
Trucking General Liability
Separate business liability coverage may address qualifying third-party claims connected with trucking activities away from driving the vehicle.
What you haul and how you operate both matter.
Truck insurance is not based on the vehicle alone. Business use, cargo, routes and contractual arrangements can change the coverage discussion.
Tractor-trailers, box trucks and other commercial trucks can have different policy requirements.
The type and value of goods hauled can affect available cargo coverage.
Local, regional and long-haul operations can be treated differently.
Owner-operators, leased drivers and fleets can require different policy arrangements.
Some risks sit outside basic vehicle liability.
Additional trucking coverage can be added when it fits the operation and is available from the insurer.
Motor Truck Cargo
Protection for qualifying loss or damage to goods being transported by the insured trucking operation.
Trailer Interchange
Physical damage protection for qualifying non-owned trailers held under a written interchange agreement.
Non-Trucking Liability
Certain leased owner-operators may need liability protection for qualifying personal use when off duty.
Downtime Options
Certain products may include rental or downtime-related benefits following a qualifying covered loss.
One truck and twenty trucks are different insurance conversations.
The number of vehicles, drivers, ownership structure and business contracts can affect how a trucking policy is arranged.
Federal requirements depend on the operation.
FMCSA insurance requirements can vary by carrier type, operating authority, cargo and vehicle type. State requirements can also apply.
Certain for-hire interstate motor carriers must maintain qualifying financial responsibility.
When federal insurance filings are required, the insurer submits the applicable filing to FMCSA.
Federal cargo filing requirements are not identical for every type of motor carrier.
Customers, brokers and equipment owners may require coverage beyond a regulatory minimum.
Several business details can affect a truck insurance quote.
Trucks & Equipment
Vehicle type, year, value and permanently attached equipment may be requested.
Drivers
Driver information and driving history may form part of underwriting.
Cargo & Routes
The freight hauled and the areas where trucks operate can affect available policy choices.
Business History
Operating history, claims information and other business details may be requested by the insurer.
The load and trailer may need protection of their own.
Commercial truck liability does not automatically mean every piece of cargo or every trailer is protected. Separate coverage may be required.
Review the type and value of freight regularly hauled.
Certain commodities or causes of loss may be restricted.
Trailer interchange coverage may apply when hauling trailers owned by another party.
Contracts can specify the insurance required for cargo or borrowed equipment.
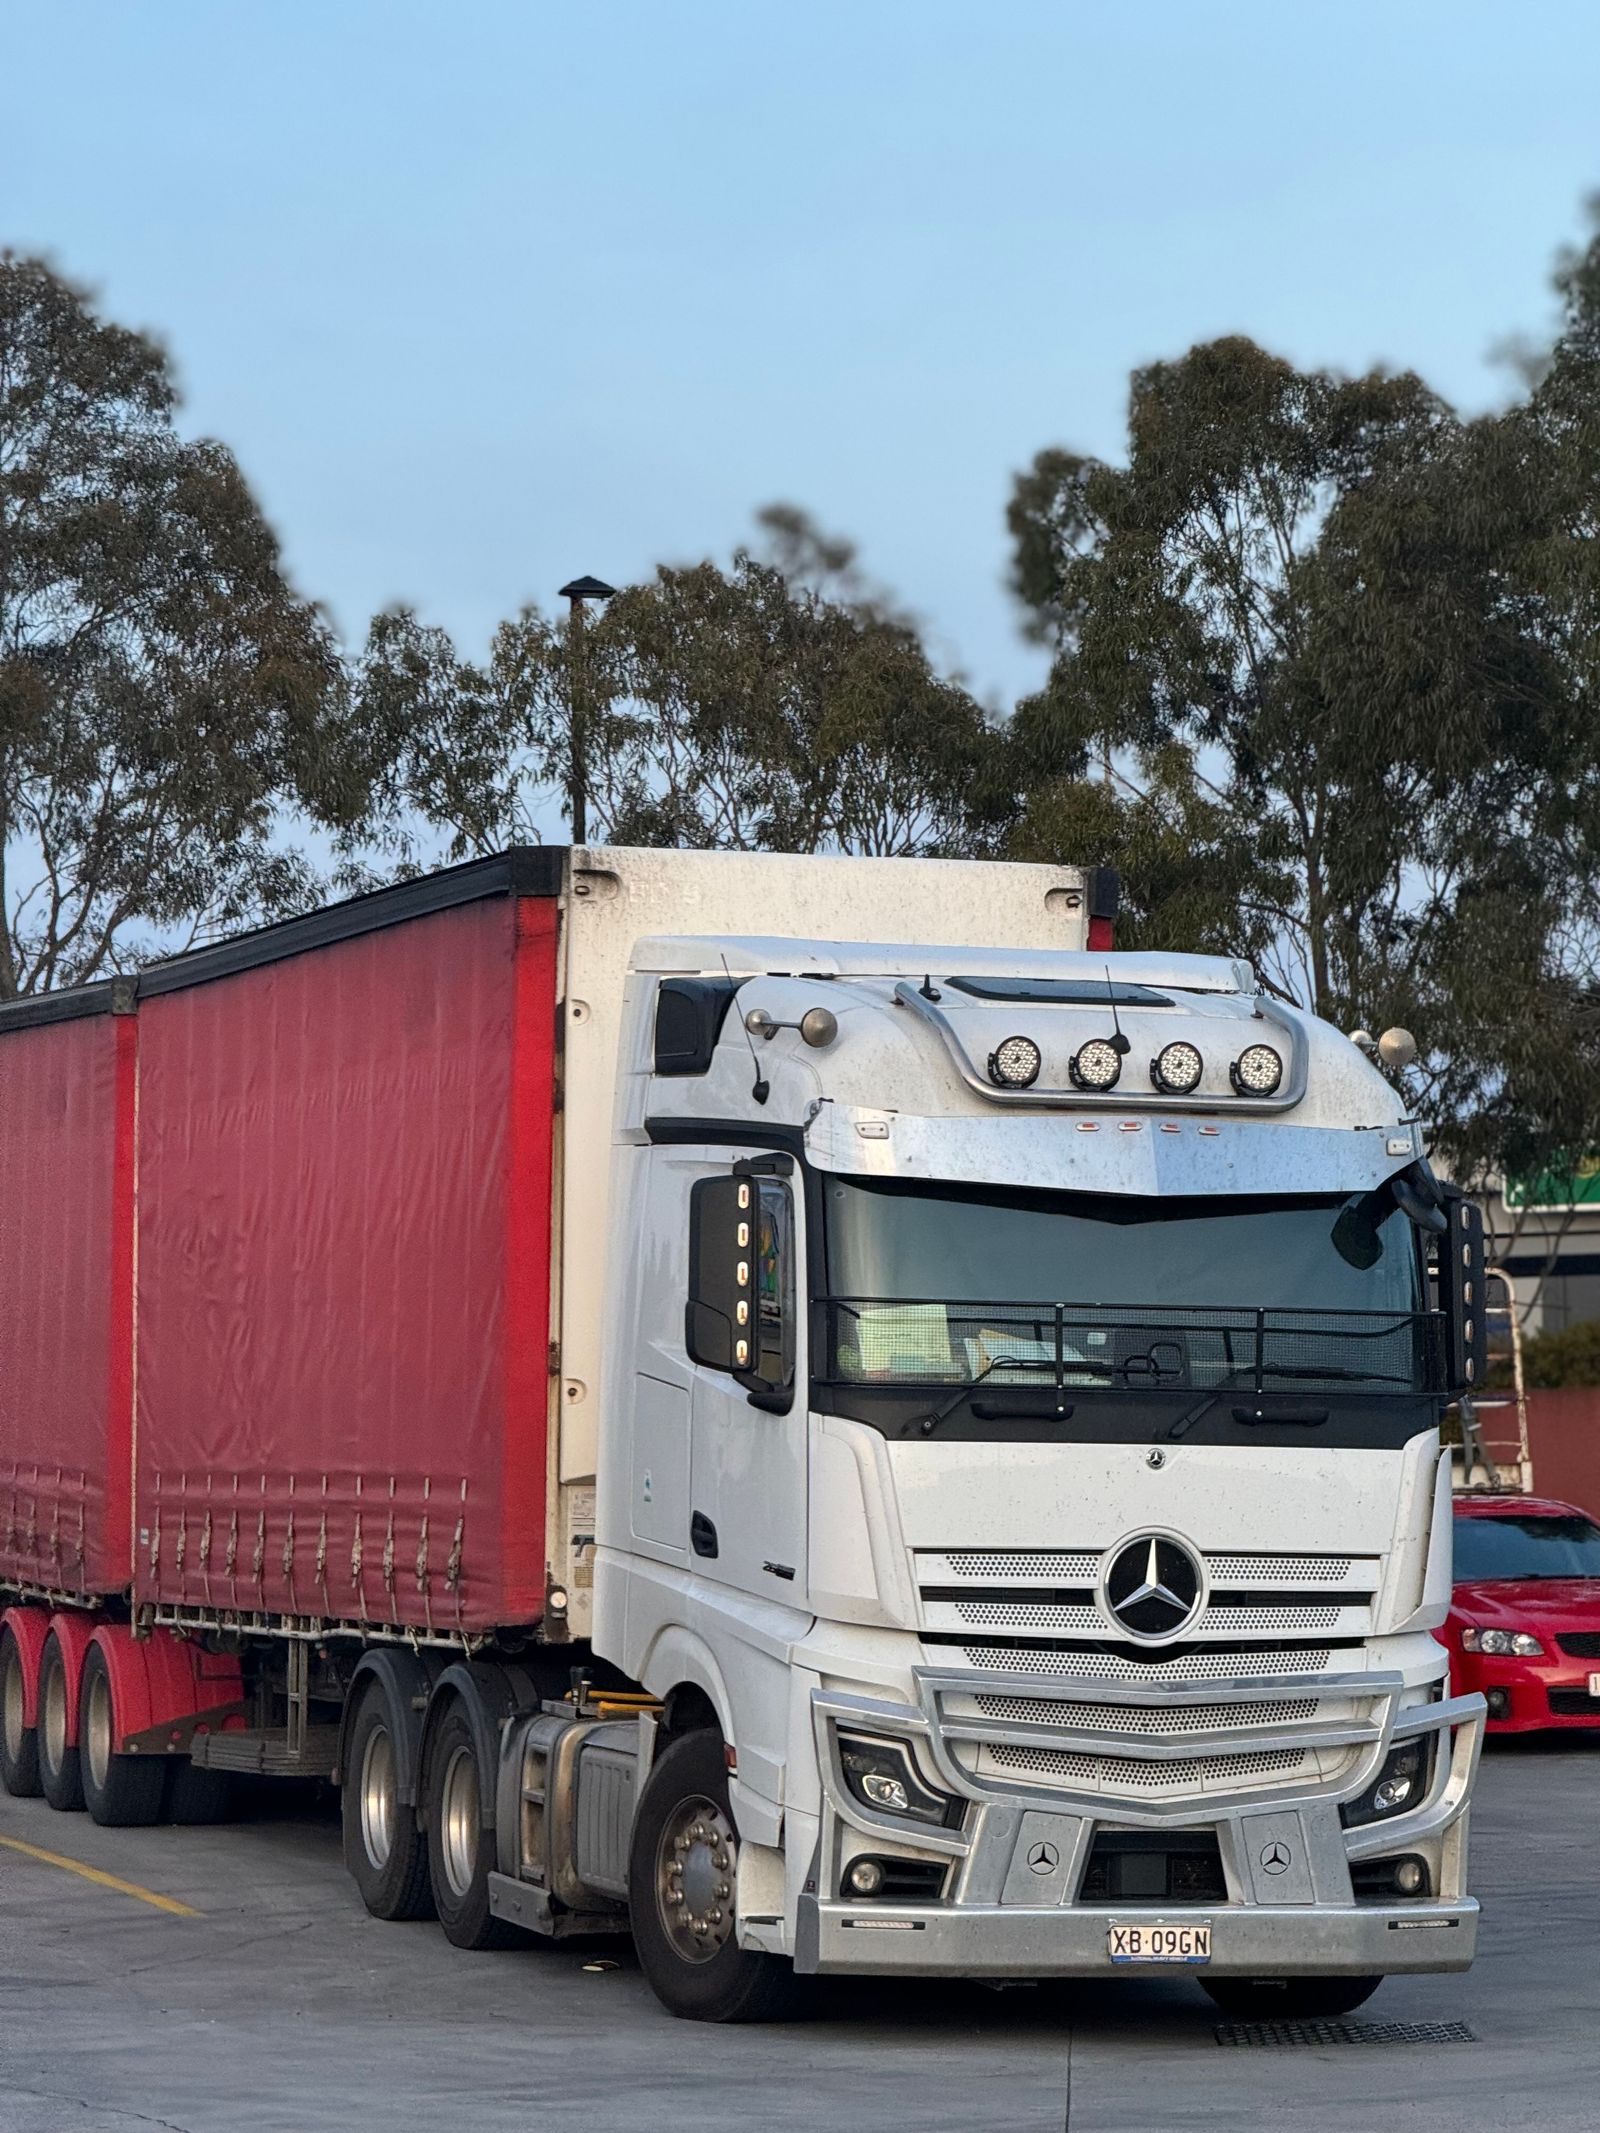
Start with the trucks, drivers and work you perform.
Business information helps identify the coverage areas that need review.
Describe the operation.
Share business use, operating radius, cargo and applicable authority information.
Review trucks and drivers.
Identify vehicles, equipment and drivers that need to be considered.
Review coverage needs.
Consider liability, physical damage, cargo and applicable truck-specific options.
Review policy details.
Check limits, deductibles, exclusions and applicable filings before selecting coverage.
Common questions.
Requirements and available coverage differ by operation and insurer.
Depending on the operation and policy, truck insurance can include commercial auto liability, physical damage, motor truck cargo, trailer interchange, non-trucking liability and other trucking-related coverage.
No. Coverage and regulatory requirements can depend on the carrier type, operating authority, cargo, vehicle and location.
No. Federal cargo filing requirements are not the same for every motor carrier. Household-goods carriers have specific federal cargo requirements, while other operations may carry cargo insurance because of business or contract needs.
Trailer interchange insurance can provide physical damage protection for a qualifying non-owned trailer while it is in the insured trucker's possession under a trailer interchange agreement.
Non-trucking liability can provide liability protection for certain leased owner-operators when a truck is being used for qualifying personal rather than business purposes.
Information may include vehicles, drivers, business use, operating radius, cargo, applicable authority information, prior coverage and other underwriting details requested by the insurer.
Keep the trucks working with coverage built for the operation.
Tell Trinity about your trucks, drivers, routes and cargo to begin reviewing available commercial truck insurance choices.